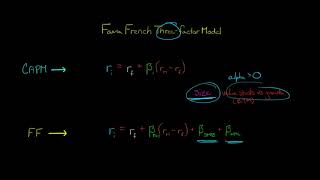Overview to Multifactor Models Vs Capm Two Factor Expected Return Example
Looking for the latest information on Multifactor Models Vs Capm Two Factor Expected Return Example? We've researched comprehensive data, records, and insights about Multifactor Models Vs Capm Two Factor Expected Return Example.
Key Details
Explore the primary sources for Multifactor Models Vs Capm Two Factor Expected Return Example.
Latest News
Stay updated on Multifactor Models Vs Capm Two Factor Expected Return Example's latest milestones.
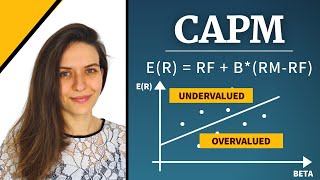
Explaining the Capital Asset Pricing Model (CAPM) & Security Market Line (SML)
CAPM Formula Explained | Beta and Required Return Made Simple
What Is the Arbitrage Pricing Theory
CAPM - What is the Capital Asset Pricing Model
CAPM and Diversification - Financial Markets by Yale University #18
Factor Models 7: Multifactor Model Extensions to the CAPM
CAPM Explained - What is the Capital Asset Pricing Model (AMZN Example)
Fama French Three Factor Model
Factor Models Explained How Quants Decompose Every Return final
Arbitrage Pricing Theory and Multifactor Models of Risk and Return (FRM P1 – Book 1 – Chapter 12)
The Arbitrage Pricing Theory and Multifactor Models of Risk and Return (FRM P1 2025– Bk 1 – Chptr 6)
Expert Insights
Data is compiled from public records and verified media reports.
Last Updated: September 30, 2026
Final Thoughts
For 2026, Multifactor Models Vs Capm Two Factor Expected Return Example remains one of the most searched-for information profiles. Check back for the newest reports.
Disclaimer: Disclaimer: All information is compiled from publicly available data, media reports, and analysis. Actual details may vary.
Summary
Supplement your readings with this video providing an overview of using Level II CFA Portfolio Management: learn how In this video, Ryan O'Connell, CFA, FRM, provides an in-depth explanation of the The (APT) improves upon the pricing ( This video is part of an online course, Financial Markets, created by Yale University. Learn finance principles to understand the ... In this final lecture in a series on asset pricing In this video we'll explain what the This video discusses the Fama-French three- Asset prices are driven by hidden underlying forces. We explore how Data Scientists use Learn Arbitrage Pricing Theory and Ace FRM Part 1 Book 1 – Foundations of Risk Management with this deep dive into Arbitrage Pricing Theory (APT) and
Multifactor Models Vs Capm Two Factor Expected Return Example.pdf
What is the most accurate information about Multifactor Models Vs Capm Two Factor Expected Return Example?
Our platform aggregates the most comprehensive and up-to-date insights, ensuring you get relevant details about Multifactor Models Vs Capm Two Factor Expected Return Example.
Why is Multifactor Models Vs Capm Two Factor Expected Return Example trending right now?
Interest in Multifactor Models Vs Capm Two Factor Expected Return Example has surged recently as more people seek reliable resources, related media, and detailed analysis.
Where can I find related media and updates for Multifactor Models Vs Capm Two Factor Expected Return Example?
You can explore extensive galleries, video summaries, and related content directly on this page.
How often is the content about Multifactor Models Vs Capm Two Factor Expected Return Example updated?
We regularly update our database with the latest information, media, and analysis related to Multifactor Models Vs Capm Two Factor Expected Return Example.